Table of Content
Our comprehensive database of USDA eligible listings and market info gives the accurate view of your home value. Please alert me as soon as a new USDA eligible home hits the market in the area of my choice. To browse in your areas of interest, look for properties by location. Homes with an underground pool will NOT qualify for a USDA loan.

Buyers in large cities and more densely populated suburbs aren’t eligible for these loans, but many living in surrounding towns and cities may be. An area with a population of 35,000 or less can be considered “rural” in the USDA’s eyes. Perhaps you feel more at home surrounded by pastures than pavement. If so, buying a home might be well within reach, thanks to the U.S. In fact, the USDA might have one of the government’s least-known mortgage assistance programs. To assess potential eligibility of an applicant/household, click on one of the Single Family Housing Program links above and then select the applicable link.
FHA Home Loan Information
Each fiscal year, the Agency targets a portion of its direct and guaranteed farm ownership and operating loan funds to beginning farmers and ranchers. FSA makes direct and guaranteed farm ownership and operating loans to family-size farmers and ranchers who cannot obtain commercial credit from a bank, Farm Credit System institution, or other lender. FSA loans can be used to purchase land, livestock, equipment, feed, seed, and supplies. Loans can also be used to construct buildings or make farm improvements.

The amount you can earn to have access to USDA loans is limited and varies by location and household size, so use this tool for more specific guidance. Payment assistance is a type of subsidy that reduces the mortgage payment for a short time. The amount of assistance is determined by the adjusted family income. This site is used to evaluate the likelihood that a potential applicant would be eligible for program assistance.
USDA Loan Property Requirements 2022
For family with 1-4 members current income limits in Orlando, FL $90,300/- whereas for a family with 5-8 members income limits go upto $119,200/-. Learn more about FHA home loans below, including the requirements to get an FHA loan, the 2022 FHA loan limits, and an FHA mortgage calculator. The USDA outlines specific minimum property requirements (MPR’s) to ensure the house you buy is a safe and sound investment.

If you find discrepancies with your credit score or information from your credit report, please contact TransUnion® directly. To learn more about USDA home loan programs and how to apply for a USDA loan, click on one of the USDA Loan program links above and then select the Loan Program Basics link for the selected program. Figuring out the family income, and if you meet the requirements is pretty straightforward – where most people find difficult about USDA homes, is finding a PROPERTY that qualifies for this financing! It doesn’t mean that you have to find a FARM… but it does mean that you will need to located a home that sits in a LESS densly populated area. If you already have way too many loans, your lender will perceive you as a high-risk borrower since your debt burden is already on the higher side. To increase your Home Loan eligibility, clear some loans before applying for a new one.
Farm Loans
And those without a credit score, or a limited credit history, can qualify with “nontraditional” credit references, such as rental and utility payment histories. On top of that, you can use both guaranteed and direct funds to pay for your closing costs. You can also get a USDA loan to help refinance a qualifying property. While the home value itself won’t directly determine the property eligibility, it will play a role in whether or not you can actually get it.
In fact, you might be surprised at just how much of the country is actually eligible for these loans. NerdWallet strives to keep its information accurate and up to date. This information may be different than what you see when you visit a financial institution, service provider or specific product’s site. All financial products, shopping products and services are presented without warranty. When evaluating offers, please review the financial institution’s Terms and Conditions.
The USDA guaranteed loan, which is also known as the “USDA rural development loan”, is only available to finance rural properties. What is technically considered rural is any town, city, place, or village outside of a major urban/metropolitan area, and that has a population that does not exceed 20,000 inhabitants. You can use the USDA eligibility search to check the eligibility of an exact address, or otherwise view by region, which will highlight ineligible areas. We can walk you through how to find USDA eligible homes for sale. Generally speaking, a single family residence, which does not produce income, will be owner occupied, and is located within a designated rural development zone. Once you’ve used the USDA loan map to determine if a property is eligible, your next step is to confirm you meet income requirements.
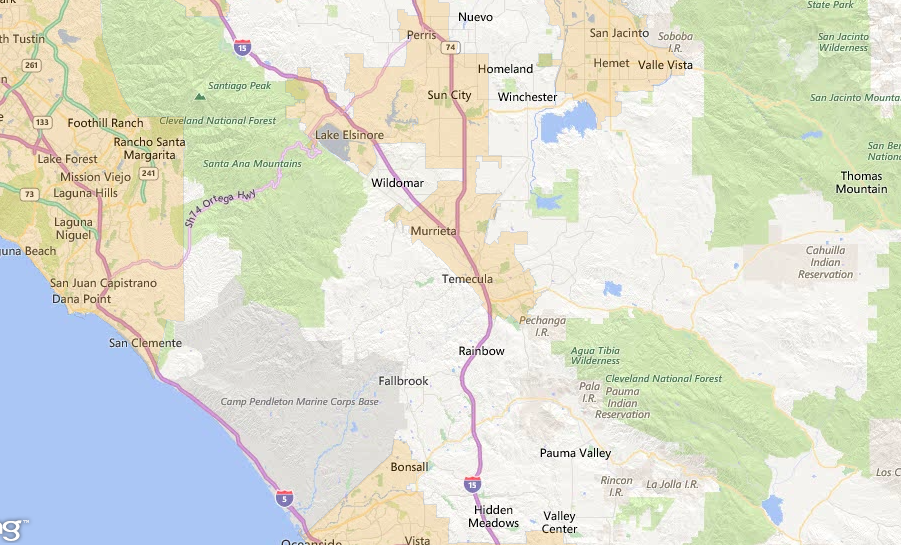
To verify the home is in good repair, a qualified appraiser will inspect and certify that the home meets current minimum property requirements set forth in HUD's Single Family Housing Policy Handbook. The USDA wants to ensure that the home you choose meets certain property requirements to protect the borrower's interest and well-being. If your prospective home falls near or in an area that does not appear to meet the rural designation, a USDA-approved lender can verify the address through the USDA's online portal. Our agency has many specialized areas, USDA home loans is our real specialty and these are also the first choice of our customers. Talk to a USDA mortgage expert and see if you can qualify for a USDA loan. All the non peach areas in the map are eligible for a USDA home loan.
All foundational, structural, mechanical, water systems, heating and cooling, as well as potential termite/pest issues must be closely inspected. Please select your state in the dropdown menu above to find your local contact for this program. There are no other additional requirements at the national level. If there are additional state-specific requirements they will be listed above.
Additionally, these MPR’s help the USDA thoroughly vet the property for the loan guarantee. Only properties within USDA-designated rural areas can be purchased with a USDA home loan. The definition of “rural” doesn’t just mean farmland and homes in very remote areas. There are actually many suburban properties that are eligible for USDA loans as well. Some lenders will instead use compensating factors to show your creditworthiness in underwriting. Documenting a healthy savings account and carrying very little debt can go a long way.
This map is a helpful guide, but the USDA will make a final determination about property eligibility once there's a complete loan application. If you do not meet your lender's income eligibility requirements, disclose all additional income sources in your application. USDA provides homeownership opportunities to rural Americans, and home renovation and repair programs. USDA also provides financing to elderly, disabled, or low-income rural residents in multi-unit housing complexes to ensure that they are able to make rent payments. If you or the property does not qualify for a USDA loan we can also help with FHA, Conventional or other loan programs.
Loan closing is relative to you sending your purchase contract. From the time when we recieve purchase contact it may take approx 5-6 weeks to close a loan in Orlando, FL. Below are some of the most frequently asked questions about USDA loans.


No comments:
Post a Comment